Own productTrading / research
Insider Radar, smart-money signals with an honest track record
26Sources in one score
1/7/30 dOutcome checks per signal
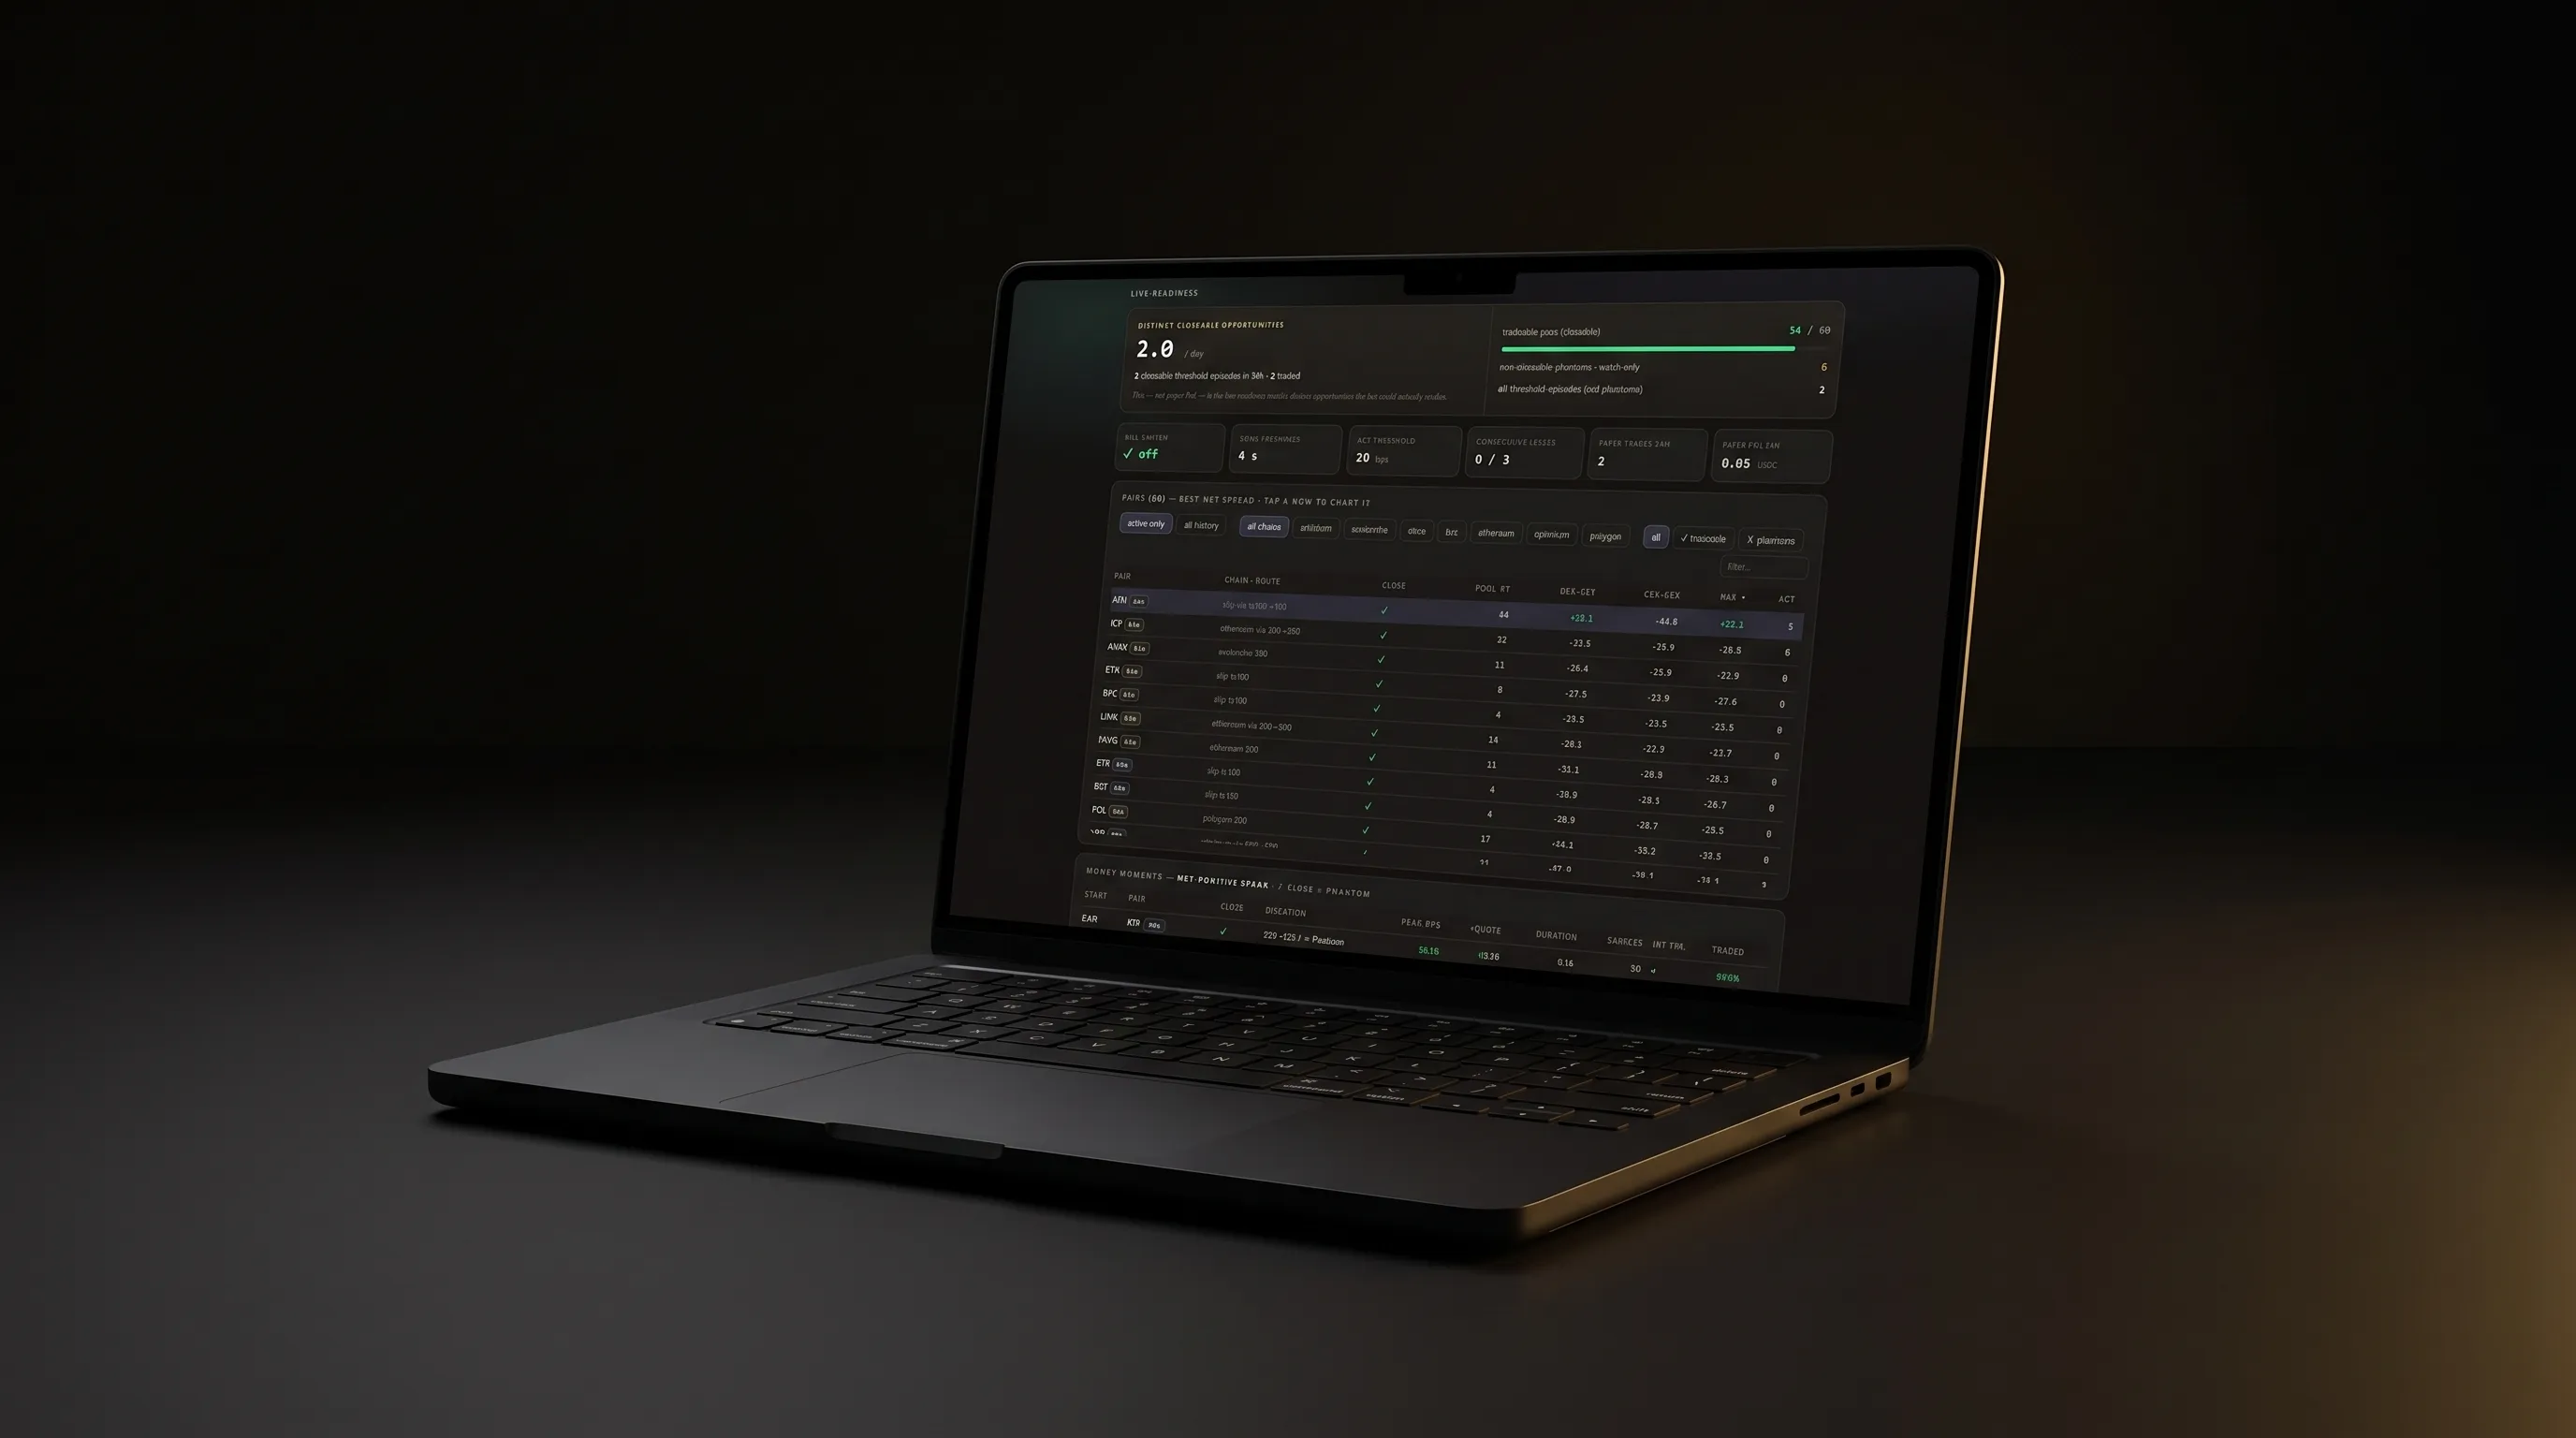
arb-bot prices two CEXes against Uniswap v3 on seven chains and subtracts six lines of cost before it prints a number, journaling every positive spread the second it appears, paper only with no orders and no API keys.
Auto-discovered, shown live on the dashboard
Built with Claude Code in 4 weeks
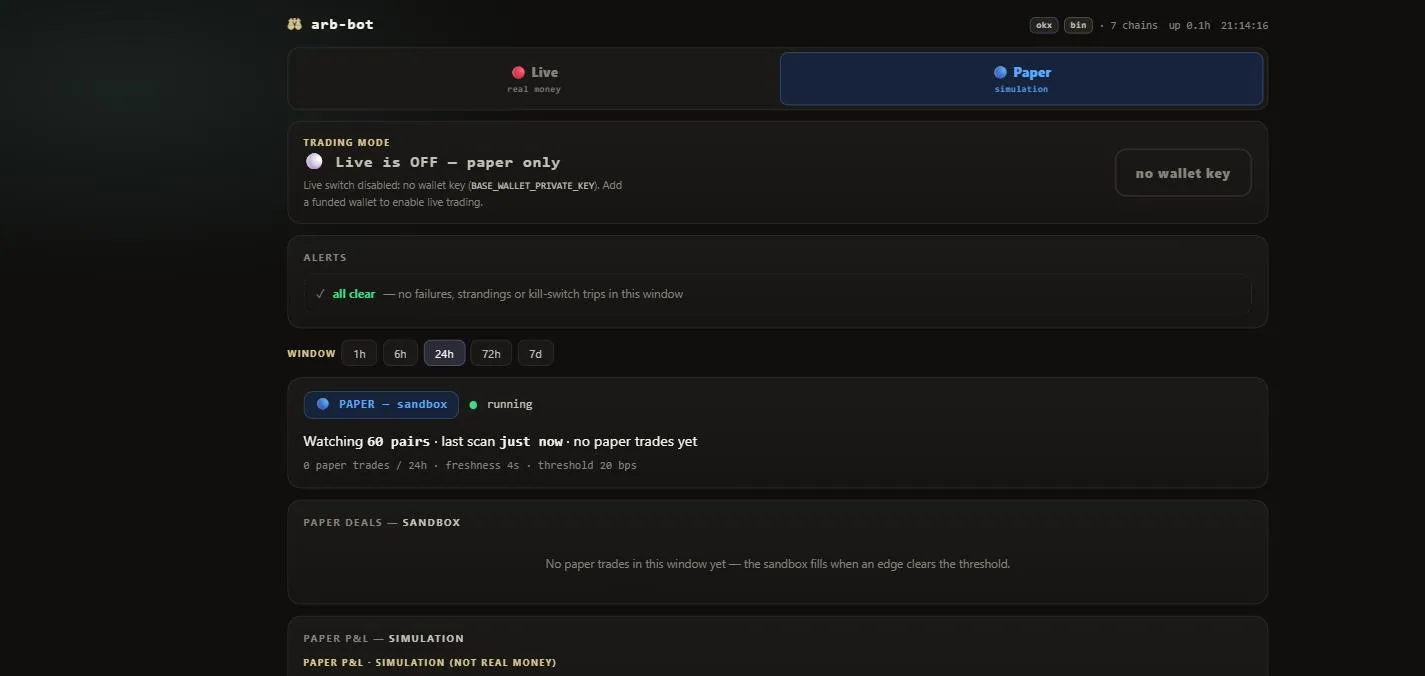
Live trading is off by construction. There is no wallet key, so the bot can quote, price and journal but never move funds. The header says what it is watching right now, how fresh the last scan is and whether the kill-switch has tripped.
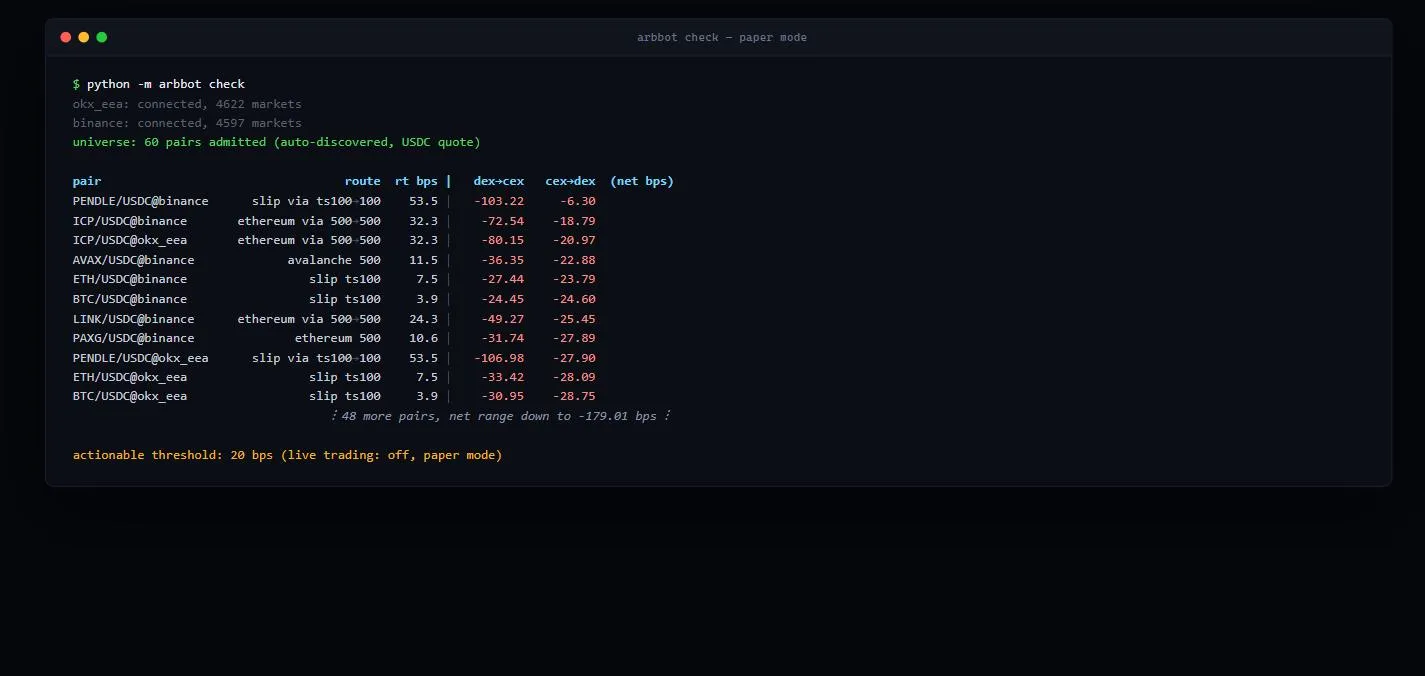
arbbot check connects to both venues, quotes the route in both directions and prints the net basis points after the taker fee, the order-book walk, DEX fee and impact, gas, rebalancing and a safety buffer. Majors sit deep in the red most of the time, and the honest number shows it at once.
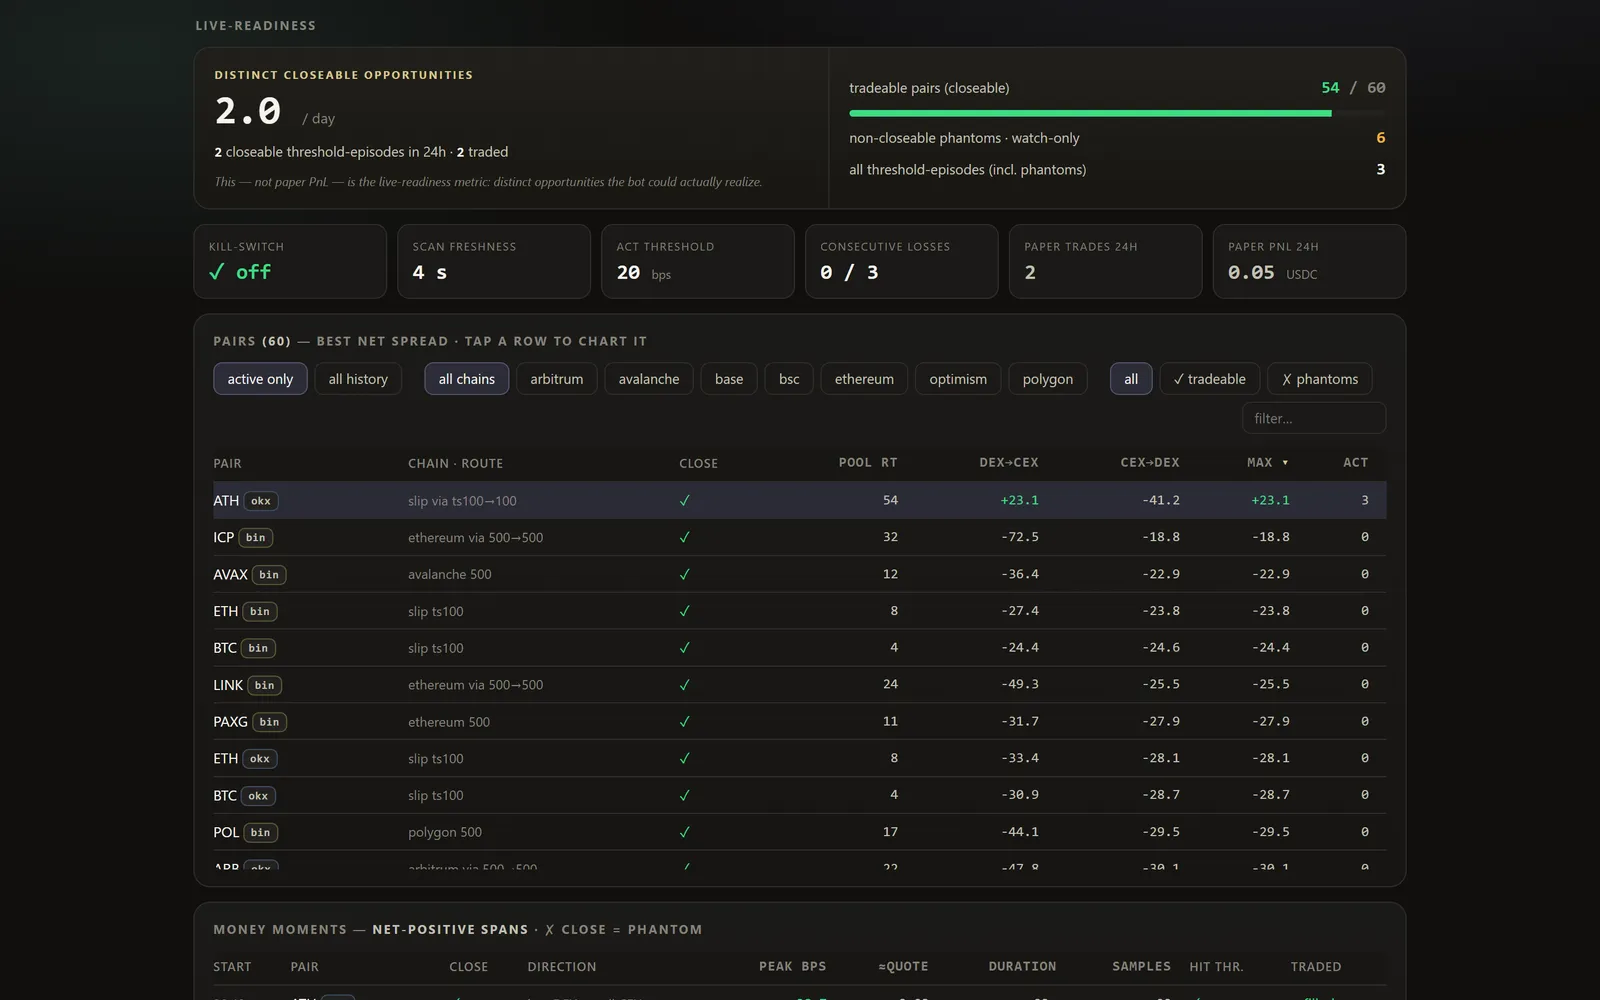
Instead of paper PnL, the dashboard counts distinct threshold episodes, the ones the bot could really have closed, split off from phantoms that vanish before a fill. Pairs are ranked by their best net spread, with the kill-switch, scan freshness and the loss streak on the same screen.
The gap between two venues looked like free money right up to the fee line.
60 pairs quoted live, every cost priced in, the honest number in Telegram the second it turns positive.
01Context
A CEX quote and a DEX quote for the same asset rarely match, and the gap looks like free money until a taker fee, the DEX's own price impact, gas and the cost of rebalancing inventory eat most of it. arb-bot starts from that honest number instead of the gross one, on venues it can actually use: OKX EEA (the MiCA-licensed OKX entity for Europe) and Binance spot.
02How it works
Discovery re-verifies each candidate pair on-chain for symbol and decimals, then probes liquidity with quoter round-trips at trade size; a guard compares the route's price against the CEX ticker and drops anything that diverges too far. The net spread itself subtracts the CEX taker fee, a VWAP walk of the live order book, DEX fee and price impact, current gas, an amortized rebalancing cost and a safety buffer, six cost lines in all, all in Decimal arithmetic.
03Outcome
Majors sit net-negative most of the time, so arb-bot is built to catch short dislocations instead: every positive spread is journaled the instant it appears, the scan cadence bursts to once a second while it holds and a paper fill re-quotes both venues after real latency before it books a result. The universe stays auto-discovered and capped at 60 pairs, the dashboard shows it running live and nothing here has placed a real order, opened a transaction or needed an API key. None of it is investment advice.
ANM SOLUTIONS / CONTACT US
First 30-minute call is free. We scope it, you decide.